

By La Verdad Express
Ottawa, Ontario — October 28, 2026
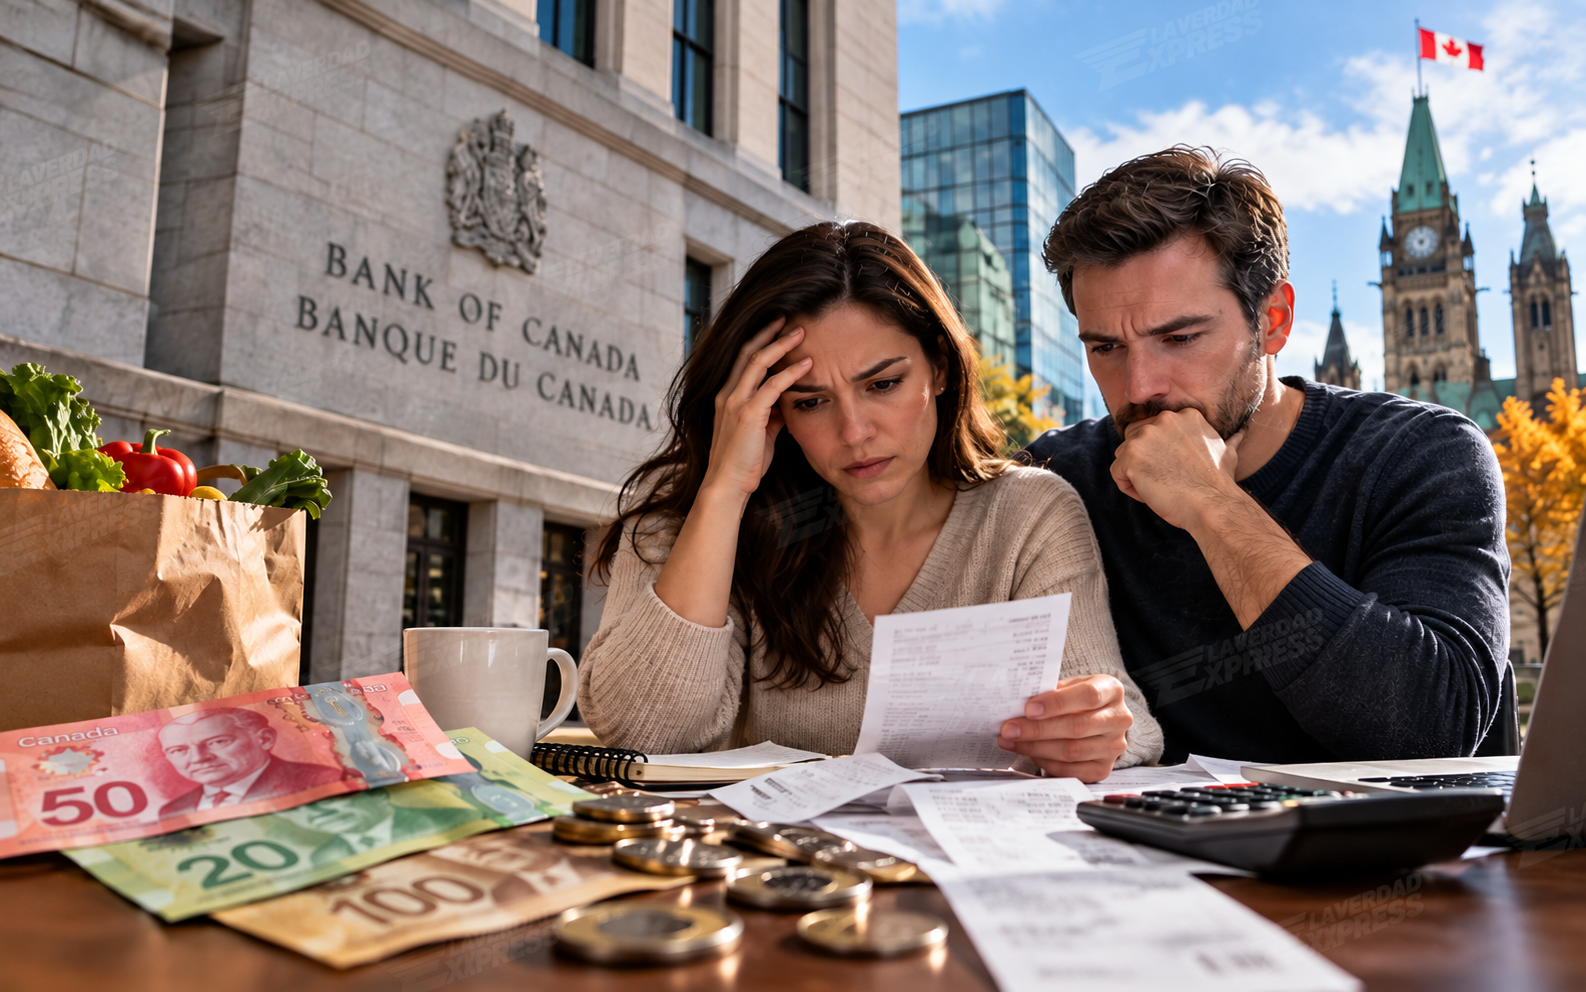
Canadians are waking up today to another major Bank of Canada decision — and once again, households may be forced to absorb the consequences of an economy caught between stubborn inflation and weakening consumer confidence.
At 9:45 a.m. Eastern Time, the Bank of Canada will announce its latest decision on the overnight rate and release a new Monetary Policy Report outlining its updated outlook for inflation, growth and the Canadian economy. Governor Tiff Macklem and Senior Deputy Governor Carolyn Rogers are scheduled to hold a press conference at 10:30 a.m.
The policy rate currently stands at 2.25 per cent after the Bank left it unchanged in September.
But pressure for a rate increase has grown.
A Reuters poll published ahead of today’s decision found that 19 of 34 economists expected the Bank to raise its benchmark rate by 25 basis points to 2.50 per cent. That would represent the first increase in roughly a year.
For millions of Canadians, however, the issue is not simply whether the rate moves by one-quarter of a percentage point.
The real issue is how much more financial pressure households can realistically absorb.

Inflation is rising again
Statistics Canada reported that annual inflation rose to 3.1 per cent in September, up from 3.0 per cent in August.
The increase was driven largely by gasoline prices, which were 27.8 per cent higher than a year earlier.
Transportation costs overall jumped 8.4 per cent year over year.
That matters because higher fuel costs rarely stay confined to the gas pump.
They affect transportation, deliveries, logistics, business expenses and ultimately the prices consumers see throughout the economy.
At the same time, the inflation picture is more complicated than the headline number suggests.
When gasoline is excluded, inflation was 2.2 per cent in September — much closer to the Bank of Canada’s target.
That creates an uncomfortable dilemma.
If the Bank reacts aggressively to headline inflation driven largely by energy prices, it risks increasing borrowing costs for households already dealing with expensive mortgages, loans and everyday living costs.
If it waits too long, inflation expectations could become more deeply embedded.
Canadians are already pulling back
The Bank of Canada’s own consumer survey reveals how fragile household confidence has become.
Consumers reported that inflation expectations remain elevated, with trade tensions and energy prices continuing to dominate concerns.
More importantly, spending intentions deteriorated from already weak levels.
Canadians told the Bank they were reducing discretionary purchases, eating out less frequently, searching for lower-cost alternatives and delaying major purchases because of high prices and economic uncertainty.
That should be a warning sign.
A country cannot endlessly depend on households to absorb every economic shock.
Higher food costs.
Higher transportation costs.
Higher housing costs.
Higher borrowing costs.
Higher taxes and tariffs.
Eventually something gives.
A rate hike would hit households directly
If the Bank raises the policy rate today, the effect would not remain inside financial markets.
Banks typically respond by adjusting prime lending rates, which can affect variable-rate mortgages, lines of credit and certain other loans.
For homeowners already stretched by high housing costs, even a modest increase can add further pressure to monthly budgets.
For businesses, higher borrowing costs can discourage expansion and investment.
For consumers, they can make vehicles, renovations and major purchases more expensive.
The irony is difficult to ignore.
Canadians are already spending less because prices are too high.
Raising borrowing costs further could weaken that spending even more.
The Bank is fighting inflation Canadians did not create
This is where the debate becomes more uncomfortable.
Much of the inflation currently worrying Canadians is not being generated by families suddenly spending recklessly.
Energy prices have risen sharply.
Trade tensions between Canada and the United States have created additional cost pressures.
Canadian counter-tariffs are also adding costs to parts of the economy.
The Bank itself has acknowledged that tariffs and energy prices are driving inflation expectations higher.
Yet monetary policy has essentially one major weapon: interest rates.
And when that weapon is used, the burden falls heavily on borrowers.
Homeowners.
Families.
Small businesses.
People carrying lines of credit.
People trying to finance a vehicle.
People trying to enter the housing market.
That is the central contradiction facing Canada today.
The sources of inflation may be global and structural.
But the financial pain of fighting inflation is often intensely personal.
Weak growth makes the decision even harder
The Canadian economy is not operating from a position of overwhelming strength.
Economists surveyed by Reuters expected growth to slow considerably after a stronger second quarter, with annual growth estimated at only around 1 per cent for 2026.
That means the Bank faces a dangerous balancing act.
Raise rates too aggressively and economic activity could weaken further.
Move too slowly and inflation could remain elevated.
There is no painless choice.
But there is also no justification for ignoring the condition of Canadian households.
La Verdad Express Analysis
The Bank of Canada has a mandate to protect price stability.
That responsibility matters.
Allowing inflation to remain uncontrolled would ultimately hurt households even more.
But monetary policy cannot become an automatic response that assumes Canadians always have additional financial capacity.
They do not.
The Bank’s own surveys show consumers are already cutting back.
People are spending cautiously.
Major purchases are being postponed.
Economic uncertainty remains high.
And yet Canadians continue to face pressure from food, transportation, housing and borrowing costs.
If the Bank chooses to increase rates today, it must clearly explain why imposing additional borrowing costs is preferable to allowing more time for energy-driven inflation to settle.
It should also explain how it intends to avoid pushing already cautious households deeper into financial stress.
Canada cannot fight every global shock by squeezing domestic consumers harder.
Interest rates may be necessary medicine.
But medicine becomes dangerous when the dosage ignores the condition of the patient.
Today’s decision should therefore be judged not only by whether inflation eventually moves toward 2 per cent.
It should also be judged by what happens to Canadian households along the way.
La Verdad Express will update this report immediately after the Bank of Canada releases its official decision this morning.




Leave a Reply